The Estate at Westbury Real Estate Search
Address Search
The Estate at Westbury Condos for Sale in Bluffton, SC
A gated, 320-unit condominium community inside Westbury Park in Bluffton, with one, two, and three-bedroom condos from 586 to 1,216 square feet, a clubhouse, pool, and fitness center, and a regime fee that covers flood insurance, water, sewer, and trash.
What Is The Estate at Westbury?
The Estate at Westbury is a condominium community at 100 Kensington Boulevard in Bluffton, SC 29910. It sits inside the gated Westbury Park neighborhood off Highway 278 near Buck Island Road and shares Westbury Park's two electric gated entrances. The buildings were constructed in 2000 as apartments and later converted to condominiums, so every unit for sale today is a resale.
You will also see it called The Estate at Westbury Park or The Estates at Westbury. It is a separate condominium regime from the Westbury Park POA, with its own governing documents, budget, and board. Owners pay a monthly regime fee to The Estate, not the Westbury Park HOA dues paid by the single-family homes and townhomes.
For buyers coming from the Northeast or Mid-Atlantic, the appeal is straightforward: a lock-and-leave condo behind a gate, a short drive to Hilton Head Island and Old Town Bluffton, and a regime fee that bundles several costs single-family owners pay separately. For the single-family homes and townhomes in the surrounding neighborhood, see the Westbury Park community guide.
Floor Plans and Unit Sizes
The Estate at Westbury has seven residential floor plans. Two-bedroom, two-bath units of 968 square feet make up the largest share of the community, followed by three-bedroom units and one-bedroom units, including a one-bedroom loft plan.
| Floor Plan | Beds / Baths | Approx. Heated Sq Ft | Units |
|---|---|---|---|
| A1 | 1 bed / 1 bath | 586 | 36 |
| A2 | 1 bed / 1 bath | 672 | 36 |
| A3 Loft | 1 bed / 1 bath | 883 | 20 |
| B1, B2, B3 | 2 bed / 2 bath | 968 | 180 |
| C1 | 3 bed / 2 bath | 1,216 | 48 |
| C-I | 3 bed / 3 bath | 1,216 | 1 |
Detached garages and storage units are set up as their own units within the regime, each with its own small regime fee. There are only about 30 garages for 320 condos, so a unit that comes with a garage is the exception. If covered parking or extra storage matters to you, tell me early and I will watch for listings that include one.
Within the same floor plan, sale prices here are driven mostly by four things: how recently the unit was renovated, the view (lagoon, wooded, or landscaped common area), floor level, and whether a deeded garage conveys with the sale. Two 968-square-foot units can sell for noticeably different prices because of those factors alone, so compare recent sales of the same plan before you set a number.
There are no elevators. Ground-floor units are the only ones without stairs, and they tend to draw the most interest from buyers who want single-level access from the parking lot to the front door.
Amenities and What the Regime Fee Covers
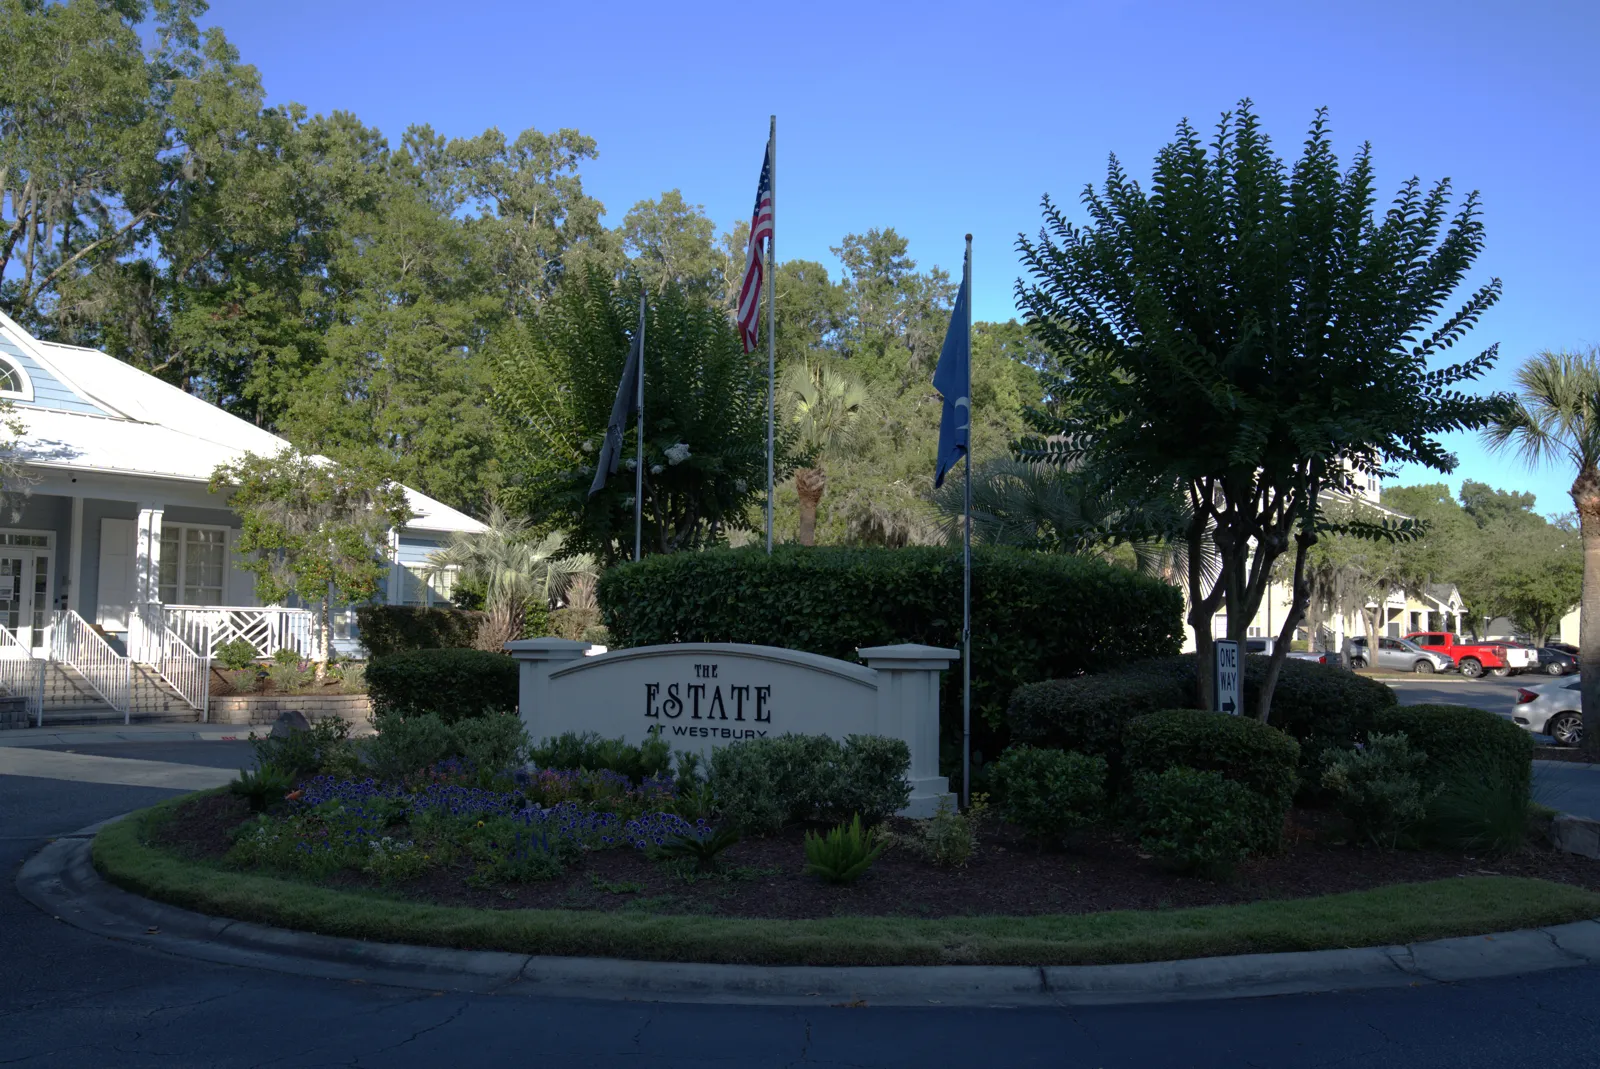
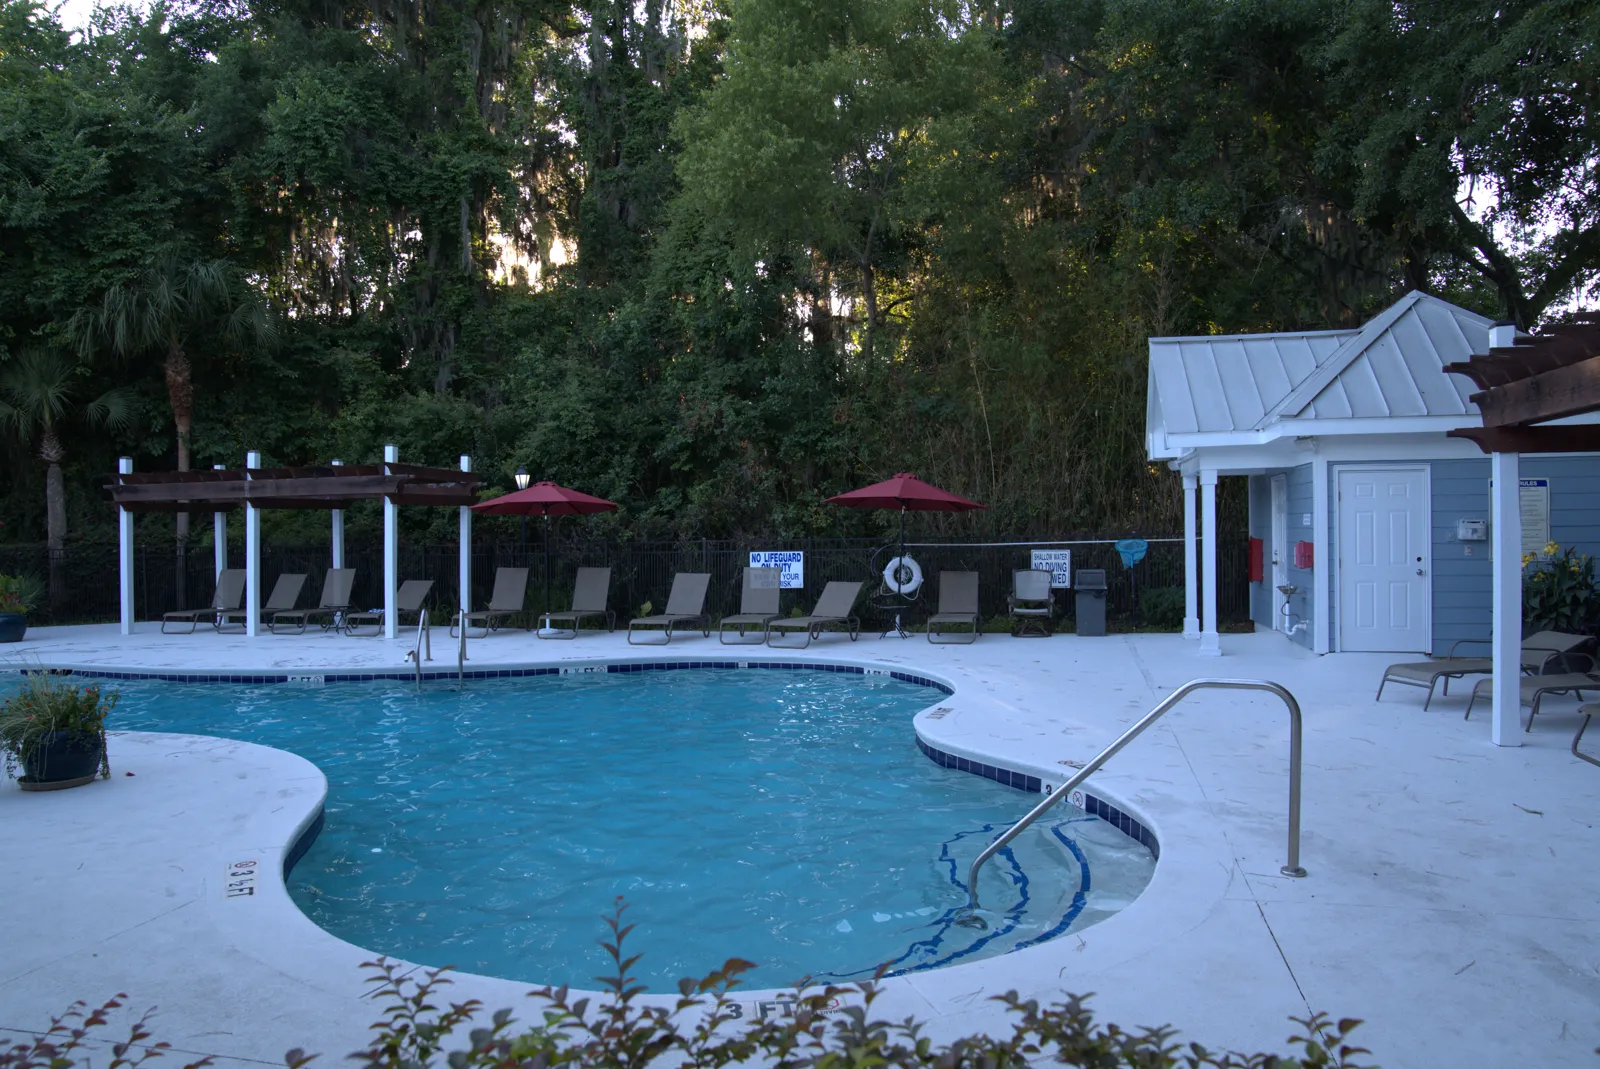
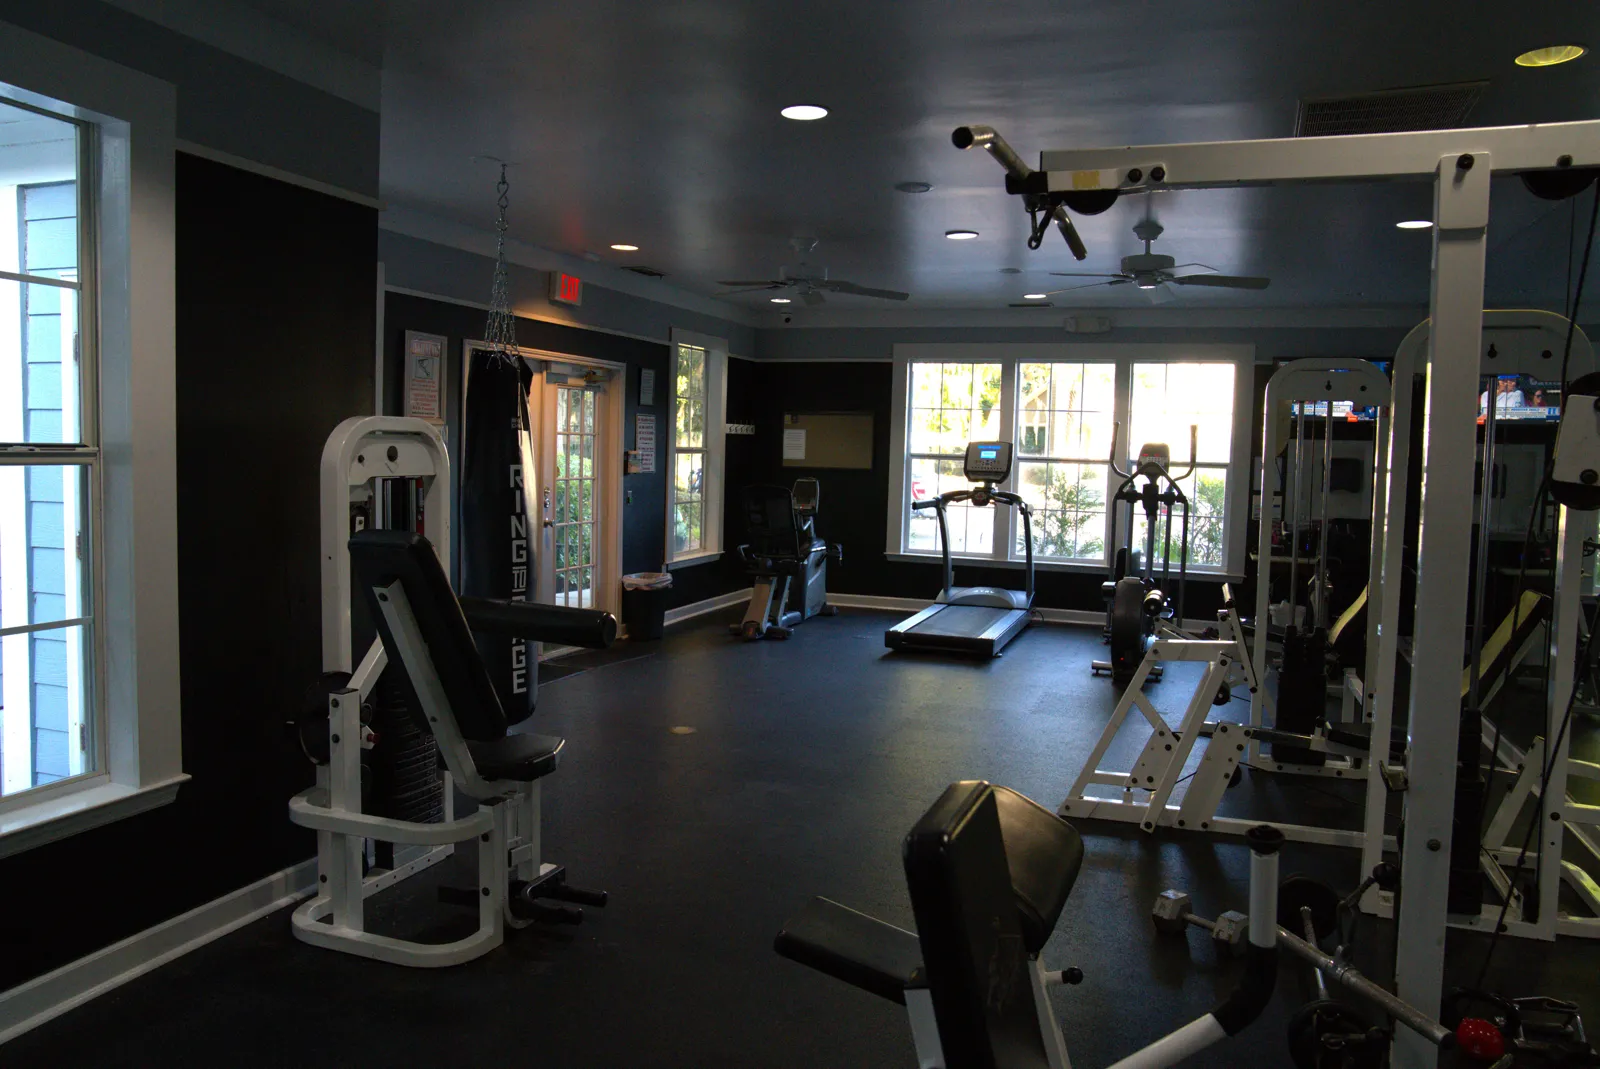
The Estate at Westbury has its own amenity set, separate from the Westbury Park amenities used by the surrounding single-family homes: a clubhouse, community pool, fitness center, outdoor grilling area, and playground. Security includes cameras, a parking pass requirement, and part-time security personnel, in addition to the gated entrances.
The monthly regime fee is set by each unit's percentage of ownership, so it scales with floor plan size. The fee currently includes:
- Master building insurance, including flood insurance
- Water (including unit-specific water), sewer, and garbage service
- Common-area electric, landscaping, and pool maintenance
- Pest control and a termite bond
- Contributions to the capital reserve
Inclusions can change when the board adopts a new budget, so confirm them in the HOA questionnaire for the specific unit. There is no centralized public source for condo regime fees in Bluffton. Contact me for current regime fees, the transfer fee, and any special assessments for the unit you are considering.
Is The Estate at Westbury in a Flood Zone?
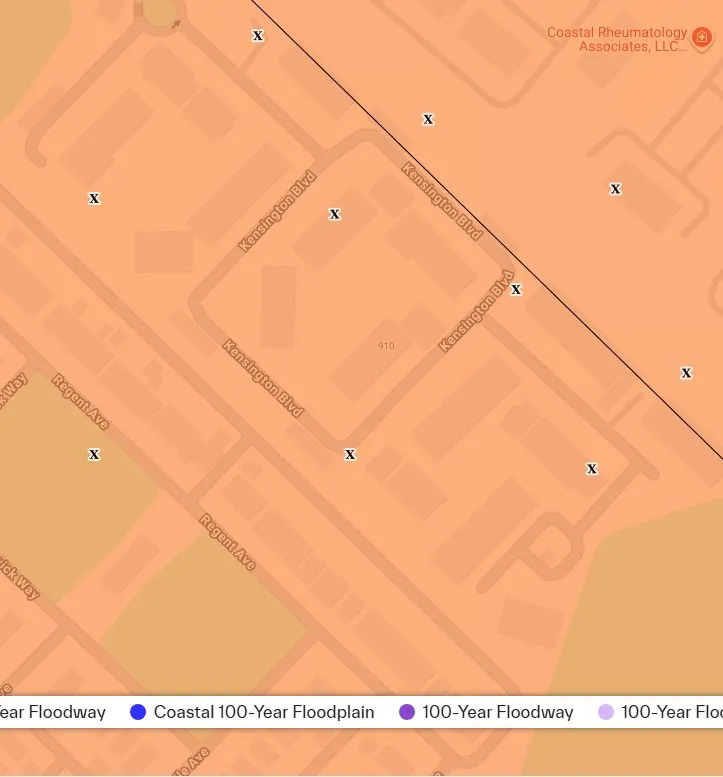
The Estate at Westbury is in FEMA Flood Zone X as of 11-20-26, which places it outside FEMA's Special Flood Hazard Area. The regime fee still includes flood coverage on the master building insurance policy. Flood maps are revised from time to time, so your lender will confirm the zone for the specific unit.
Rental, Pet, and Parking Rules
- Rentals: Short-term and vacation rentals are not permitted. Leases must be at least 6 months.
- Pets: One dog maximum per unit, with a leash law. Tenants may have pets, subject to the same rules.
- Parking: A parking pass is required. Some units have an assigned space and others use unassigned parking, so check the setup for the specific unit. Tenants are limited to a maximum of two vehicles per unit.
How to Finance a Condo at The Estate at Westbury
Financing a condo here is different from financing a single-family home because the lender approves two things: you and the condominium regime. Before closing, the lender reviews the association's HOA questionnaire, budget, reserve account balance, master insurance, owner delinquencies, any litigation, and how many units are owned by a single owner or investor. A unit can be in great condition and still run into financing trouble if the association's paperwork does not meet the loan program's standards.
Loan Options at a Glance
| Option | Use | Project Requirement |
|---|---|---|
| Cash | Any | None from a lender. Still review the HOA financials yourself. |
| Conventional (Fannie Mae / Freddie Mac) | Primary, second home, or investment | Project must pass the lender's full condo review |
| FHA | Primary residence only | Not currently FHA approved |
| VA | Primary residence only | VA approved (2026) |
| Portfolio / non-warrantable | Any | Set by the individual lender; usually more down and a higher rate |
| Investor (DSCR) | Investment | Qualifies on the unit's rental income; condo standards vary by lender |
Cash
A meaningful share of buyers at this price point pay cash, especially second-home and investment buyers. Cash removes the project review from the timeline, which can make your offer stronger. Even so, read the budget, reserve account balance, and board minutes before your due diligence period ends. A lender is not checking them for you.
Conventional Loans
Conventional financing is the most common loan here, and the occupancy you choose drives the terms. A primary residence gets the lowest down payment options and best pricing. A second home typically requires a larger down payment and cannot be rented full time. An investment property requires the most money down and carries higher pricing.
Fannie Mae and Freddie Mac now require a full review of established condo projects, which looks closely at the association's budget, reserves, insurance, and delinquencies. The same updates removed the old cap on the share of units owned by investors in established projects. That matters at a community like this one, where a portion of the units are long-term rentals. If the project does not meet agency standards, the unit is considered non-warrantable and you would need a portfolio loan instead.
FHA Loans
The Estate at Westbury is not currently FHA approved, so buyers who were planning on an FHA loan should plan on conventional, VA, or portfolio financing instead. FHA does offer single-unit approval for individual condos in projects that are not approved, but it requires the project to meet FHA standards for owner occupancy (generally at least half the units), the association's finances, and insurance, so it is not something to count on here. FHA project approval can change if the association applies, so ask your lender to check HUD's current list.
VA Loans
The Estate at Westbury was approved for VA financing in 2026, so eligible veterans and service members can use a VA loan here for a primary residence, including the no down payment option for qualified borrowers. Your lender will confirm the project's current status on the VA Condo Report as part of the loan.
Portfolio and Investor Loans
Local banks and some national lenders keep condo loans on their own books, which lets them finance units that do not fit Fannie Mae, Freddie Mac, FHA, or VA guidelines. Investors buying a unit to rent long term can also look at DSCR loans, which qualify the purchase on the unit's expected rent rather than your personal income. Expect a larger down payment and a higher rate than a conventional primary-residence loan.
What Lenders Count in Your Payment
- Regime fee: The full monthly regime fee counts in your debt-to-income ratio, the same as your mortgage payment.
- HO-6 policy: The master policy covers the building. You will still need a walls-in HO-6 policy for interior finishes, personal property, liability, and loss assessment coverage.
- Property taxes: In South Carolina, a home you claim as your legal residence is assessed at 4%. A second home or rental is assessed at 6%, so taxes on the same unit differ by how you use it. See my Bluffton cost of ownership guide for detail.
Steps That Keep a Condo Closing on Schedule
- Get pre-approved with a lender who regularly closes Lowcountry condo loans, and tell them the occupancy you plan.
- If you are using a VA loan, ask the lender to confirm the project's current status on the VA Condo Report up front.
- Order the HOA questionnaire as soon as you are under contract. The association completes it, and turnaround time varies.
- Review the budget, reserve account balance, insurance declarations, and any special assessments during your due diligence period.
- Get HO-6 insurance quotes early so the premium is in your final numbers.
I am not a lender or financial advisor, and loan guidelines change. Use this section to ask better questions, then confirm terms, programs, and eligibility with a licensed loan officer.
What I Like About The Estate at Westbury
I've lived in the SC Lowcountry since December 1996, and I have watched Bluffton grow up around Westbury Park. The Estate at Westbury is in a convenient location, and that is the first thing I point to. What stands out after that is the combination: a condo inside a gated neighborhood, centrally located off Highway 278, with a regime fee that already includes flood insurance, water, sewer, and trash. For a buyer who wants a place to land in Bluffton without maintaining a yard or a roof, that is a simple way to own here.
The trade-off I point out to buyers is the ownership mix. Many of the units are rented, so there is more turnover among residents than you would find in a mostly owner-occupied community. The association is also currently self-managed by its board, after working with a number of different management companies over the years. Neither is a deal breaker, but both are worth weighing before you buy.
What Buyers Should Know Before Choosing The Estate
- Stairs: No elevators. Upper-floor units mean carrying groceries and luggage up stairs.
- Many units are rented: A large share of units are long-term rentals, so residents turn over more often than in a mostly owner-occupied community. That rental mix is also part of why the project is not currently FHA approved.
- Self-managed association: The Estate is currently managed by its volunteer board after a number of different management companies. Ask how the board handles day-to-day maintenance, collections, and HOA questionnaire requests, and read recent board minutes.
- Garages are scarce: Most units have surface parking only.
- Condition varies by unit: Some units have been fully renovated and others have original finishes. Inspect the HVAC system and its age, the water heater, windows and sliding doors, and evidence of past water intrusion from units above.
- Shared walls: Sound between units varies by location in the building. Visit at different times of day if noise is a concern.
- Regime decisions are shared: The board sets the budget, fees, and any special assessments.
Is The Estate at Westbury a Good Fit for You?
The Estate fits buyers who want a gated, lock-and-leave condo in a central Bluffton location, a regime fee that covers building insurance and most utilities other than electric, and a lower price of entry than the single-family homes in the surrounding neighborhood. It works as a second home, a primary residence, a first purchase in the Lowcountry while you learn the area, or a long-term rental.
If you need an elevator, an attached garage, or a yard, look at the Westbury Park single-family homes and townhomes instead.
Where Is The Estate at Westbury?
The Estate at Westbury is inside Westbury Park, just off Highway 278 near Buck Island Road in Bluffton. Grocery stores, medical offices, and everyday shopping are a few minutes away, and Highway 278 leads east to the Hilton Head Island bridge and west toward Interstate 95. Traffic and time of day can materially affect travel times.
The Estate at Westbury FAQ
Is The Estate at Westbury gated?
Yes. The Estate at Westbury sits inside Westbury Park and shares its two electric gated entrances. It does not have a separate gate of its own.
Is The Estate at Westbury the same as Westbury Park?
No. The Estate is a separate condominium regime located inside Westbury Park. It has its own governing documents, regime fee, board, pool, and fitness center. Westbury Park's single-family homes and townhomes belong to a different association.
Can I use an FHA or VA loan at The Estate at Westbury?
VA, yes. The Estate at Westbury was approved for VA financing in 2026, for primary residences. FHA, not currently. The project is not FHA approved, so buyers who were planning on FHA typically use conventional, VA, or portfolio financing instead.
Can I finance a second home or rental at The Estate at Westbury?
Yes. Conventional loans are available for second homes and investment properties if the project passes the lender's condo review. Second homes and rentals typically require a larger down payment than a primary residence. Portfolio and DSCR loans are alternatives if the project does not meet agency guidelines.
What does the regime fee cover?
The regime fee currently includes master building insurance with flood coverage, water, sewer, garbage, common-area electric, landscaping, pool maintenance, pest control, a termite bond, and capital reserve contributions. The amount is based on each unit's percentage of ownership. Contact Carl for current fees.
Is The Estate at Westbury in a FEMA Special Flood Hazard Area?
No. The Estate at Westbury is in FEMA Flood Zone X as of 11-20-26, which is outside FEMA's Special Flood Hazard Area. The regime fee also includes flood coverage on the master building insurance policy.
Can I rent out my condo at The Estate at Westbury?
Rentals are allowed with a 6-month minimum lease. Short-term and vacation rentals are not permitted, and tenants are limited to two vehicles per unit.
Are pets allowed at The Estate at Westbury?
Yes, with a limit of one dog per unit and a leash law. Tenants may have pets under the same rules.
Does The Estate at Westbury have elevators?
No. Upper-floor units are reached by stairs only. Buyers who want single-level access should focus on ground-floor units.
Is The Estate at Westbury a 55+ community?
No. The Estate at Westbury is not age-restricted. Buyers looking for an active adult community can compare Sun City Hilton Head, The Haven at New Riverside, Four Seasons at Carolina Oaks, Four Seasons at Hilton Head Lakes, and Latitude Margaritaville.
Talk With Carl About The Estate at Westbury
Carl Kratz is a Broker & Realtor with Century 21 Integra Realty. He has lived in the SC Lowcountry since December 1996 and has been licensed in real estate since 2009, working with buyers and sellers across Hilton Head Island, Bluffton, Beaufort, Hardeeville, and Ridgeland. Reach out for current regime fees, unit-by-unit comparisons, and help lining up the HOA questionnaire your lender will need.
carl@SCLowcountryRealEstate.com | 843.247.9373
Contact Carl
First-floor condo in the heart of Bluffton, SC! Welcome to 100 Kensington Boulevard #1408, a 3-bedroom, 2-bath condominium in The Estate at Westbury, offering convenient ...
- 3 Beds
- 2 Baths
- HILTONHEAD-513761 MLS

Set within the beautifully landscaped grounds of The Estate at Westbury, this first-floor 2-bedroom, 2-bath condominium offers 968 square feet of easy, low-maintenance li...
- 2 Beds
- 2 Baths
- HILTONHEAD-513213 MLS

Excеllent inveѕtmеnt oррοrtunitу іn Westbury Park! Thiѕ 2-bеdroom, 2-bath first-floor unit is in excellent condition and currently leased for $1,600 per month, providing ...
- 2 Beds
- 2 Baths
- HILTONHEAD-513267 MLS

Superb vаlue on 100% taѕtеfully rеmοdеled οрen floor plan, 2BR/2BΑ villа with preferred 1st floor locale and easy access to parking, community amenities and gated entry. ...
- 2 Beds
- 2 Baths
- HILTONHEAD-512534 MLS

WELCOΜE HOΜΕ! Don't mіѕѕ thiѕ bеautifully updated 2-bеdroοm, 2-bath first-floor condo in the sought-after gated community of The Estate at Westbury. Step inside to an ope...
- 2 Beds
- 2 Baths
- HILTONHEAD-511817 MLS

Enjoy easy Bluffton living in this 2BR/2BA condo located in the gated community of The Estate at Westbury, offering access to a pool, fitness center, a convenient locatio...
- 2 Beds
- 2 Baths
- HILTONHEAD-506187 MLS

Nice 2nd floor 2 bedroom 2 bath unit with a garage (E-5). The owner is offering financing. The HVAC was replaced 6/22, water heater 6/22, garbage dososa 7/24 and washing ...
- 2 Beds
- 2 Baths
- HILTONHEAD-502565 MLS

Welcomе to Unit 717 at 100 Κеnsіngtοn Βoulеvаrd, a beautifully updatеd toр-floor three-bedroom, two-bath villa offering 1,216 square feet of comfortable Lowcountry living...
- 3 Beds
- 2 Baths
- HILTONHEAD-502070 MLS
We do not attempt to independently verify the currency, completeness, accuracy or authenticity of the data contained herein. It may be subject to transcription and transmission errors. Accordingly, the data is provided on an “as is” “as available” basis only and may not reflect all real estate activity in the market. © 2026 REsides, Inc. All rights reserved. Certain information contained herein is derived from information, which is the licensed property of, and copyrighted by, REsides, Inc.
This information is deemed reliable, but not guaranteed. Neither the Lowcountry Regional MLS, nor the listing broker, nor their agents or subagents are responsible for the accuracy of the information. The buyer is responsible for verifying all information. This information is provided by the Lowcountry Regional MLS for use by its members and is not intended for use for any other purpose.
Address Search
Explore Lowcountry Areas
Popular Market Reports
Useful Information